If you’ve built up equity in your house, borrowing against it is one of the most common ways to pay for a backyard unit. Search home equity loan ADU Washington options and you’ll find three or four products that sound alike but work differently. The honest answer: a home equity loan can work well for an ADU, as long as the amount covers the whole project and not just the kit.
Here’s how it works, how it compares to the alternatives, what you’ll need to borrow, and the Washington rules to check before you sign anything. We’re a kit home company, not a lender, so treat this as a starting point for the conversation with yours.
How a home equity loan works for an ADU
A home equity loan gives you a set amount in one lump sum, borrowed against the equity in your house. The rate can be fixed or adjustable, and if you already have a mortgage, it becomes a second mortgage with its own payment. The Consumer Financial Protection Bureau has a plain explainer on the details.
A lump sum fits an ADU well when the costs are known up front. A kit has a fixed price, and site work can be quoted before you start, so you can borrow once for the full amount.
Home equity loan ADU Washington options compared
- Home equity loan. One lump sum, often at a fixed rate. Best when you have firm quotes for the whole project.
- Home equity line of credit (HELOC). You draw what you need, when you need it, up to a limit. Rates are usually adjustable and the payment changes with your balance. Useful when costs come in stages.
- Cash-out refinance. Replaces your first mortgage with a larger one and pays you the difference. It mostly makes sense if the new rate is close to the one you have now.
- Construction-to-permanent loan. Pays out in draws as the build progresses, then converts to a regular mortgage. Kit homes are built on a permanent foundation, so lenders treat them like site-built homes. Our guide to kit home financing covers how the draws work.
How much you’ll need to borrow
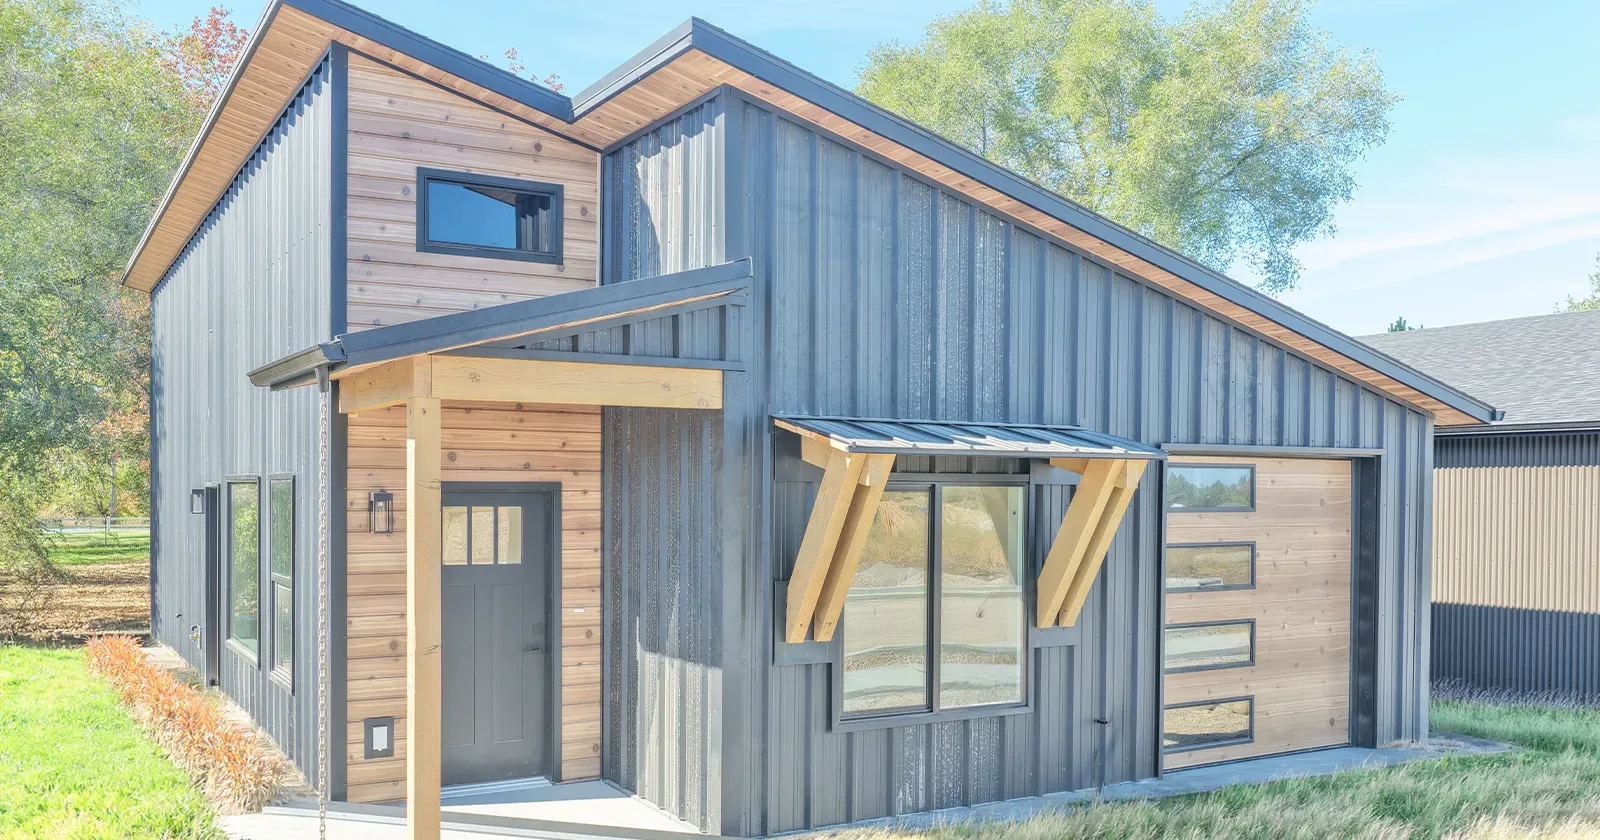
Start with the house. The Kit Culture 799 sq ft Cottage is $99,500 as a kit, or $199,500 installed on a prepared lot with optional builder labor from our partner Directional Homes. Then add what sits outside that price: the foundation, site prep, utility runs, permits, and any connection fees.
Get the site quotes before you apply. Coming back for a second loan because the sewer run cost more than expected is the mistake people regret most. Our breakdown of the total cost of a kit home shows everything that belongs in the number.
Washington rules to check before you borrow
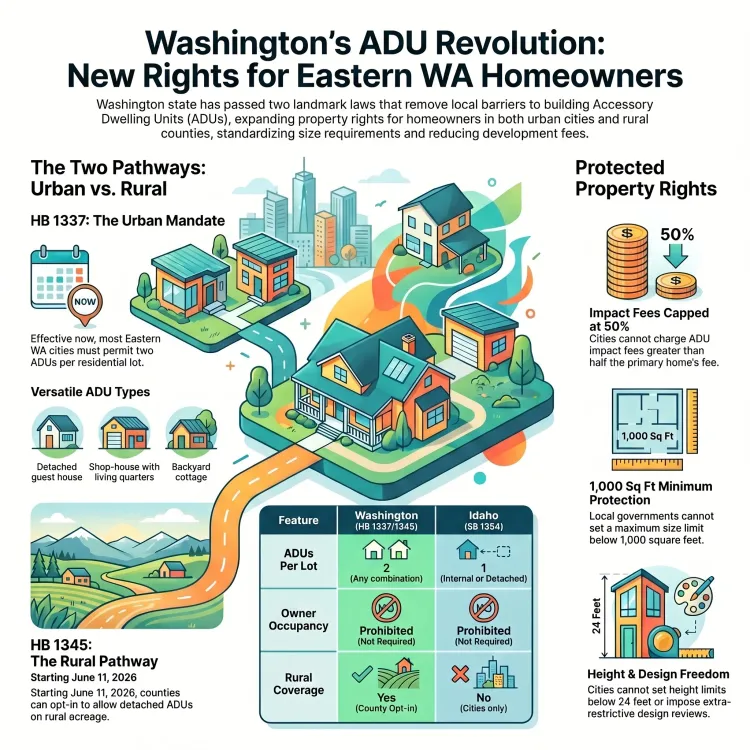
Washington’s 2023 ADU law, HB 1337, requires cities and counties planning under the Growth Management Act to allow ADUs within urban growth areas. Our guide to the Washington ADU law covers what that means for homeowners, and the Washington State Department of Commerce publishes the state’s guidance.
Your city still sets the details. Before you borrow, confirm the maximum size, setbacks, parking, rental rules, and any utility connection fees. If you’re in Spokane, our Spokane ADU permit and zoning guide is a good place to start.
Rural Washington: what changes
Outside an urban growth area, county rules apply instead of city rules, and the state law above doesn’t reach the same way. On a rural lot, an ADU may also need more septic capacity or a well that can serve two homes, which raises the amount you’ll borrow. Ask your county about ADUs on your parcel, and ask your lender early how they’ll appraise a property with two homes on it.
Home equity loan for an ADU FAQ
Can I use a home equity loan for a kit home ADU?
Yes. A kit home on a permanent foundation is permitted and inspected like any house, so it’s real property, and lenders treat it that way.
Can rent from the ADU help pay back the loan?
It can, if your city allows rentals and the numbers work at a cautious rent. Our guide to ADU rental income shows how to run the payback math.
Is the interest tax deductible?
It may be, depending on how you use the money and your own tax situation. That’s a question for your tax preparer, not a kit home company.
What if the ADU is for a parent?
Plenty of families build one for exactly that. Our breakdown of how much granny pods cost covers the budget side.
The bottom line
A home equity loan is a solid way to pay for an ADU in Washington when you know the full project cost before you borrow. Get site quotes first, check your city or county rules, and compare the loan against a HELOC and a construction loan with your lender. If you’d like a real number for the build side on your lot, give us a call.